
Share your experience of gadget insurance
Tell us whether your devices are insured, who provides the cover, and whether you have claimed. Your answers are combined with other people's and reported only as totals.
Start the mobile phone and gadget insurance surveyAbout 5 minutes. No account needed. You can stop at any time.
Types of device cover
There are several ways to protect a phone or gadget:
- Gadget insurance bought separately from an insurer, covering one or several devices against damage, loss and theft.
- Plans sold by phone networks at the time of buying a contract.
- Manufacturer protection plans that extend the warranty and add accidental damage cover.
- Retailer extended warranties sold at the till.
- Home contents insurance, which may cover devices in the home, or outside it with an add-on.
- Packaged cover with some bank accounts and premium credit cards.
These products overlap, and people sometimes pay for the same cover twice without realizing it.
What a policy usually covers
Depending on the product, cover may include:
- Accidental damage, such as a cracked screen or water damage.
- Mechanical or electrical breakdown after the manufacturer's warranty ends.
- Theft, sometimes only if force was used or the device was taken from the person.
- Loss, which is often an optional extra.
- Unauthorized use, such as calls or data used by a thief before the phone was blocked.
- Accessories up to a limit.
What a warranty already includes
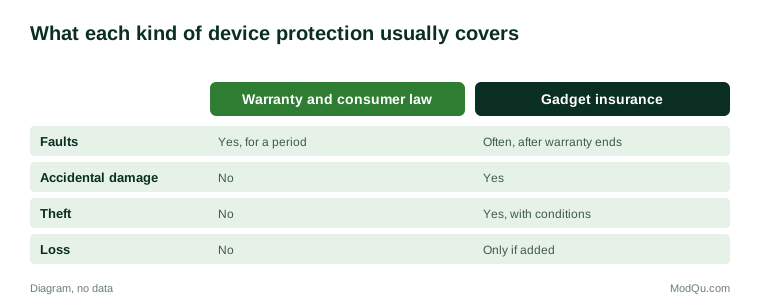
A manufacturer's warranty normally covers faults in materials or workmanship for a period after purchase. In many countries, consumer law also gives buyers rights to a repair, replacement or refund if goods are faulty, for a period that may be longer than the warranty. Warranties and these legal rights do not cover accidental damage, loss or theft.
This matters because some extended warranties mainly repeat protection the buyer already has under the manufacturer's warranty or the law.
The figure below shows what each kind of protection usually covers.
Costs: premiums and excesses
The cost of gadget cover has two parts: the regular premium and the excess paid when making a claim.
Example (hypothetical figures)
A phone costs 900. Insurance costs 12 a month, and each claim has an excess of 100. Over two years the owner pays 288 in premiums. If they crack the screen once, they also pay the 100 excess, so the total cost is 388. A screen repair without insurance would have cost 250. If the phone were stolen, the insurance would replace a 900 phone for the same 388.
People who are careful with devices may pay more in premiums than they would spend on repairs. People who often break or lose phones, or who could not afford to replace one, may value cover more.
Common exclusions and conditions
Typical exclusions and conditions include:
- leaving the device unattended in a public place;
- loss, unless loss cover was bought;
- damage from wear and tear or cosmetic scratches;
- not reporting theft to the police within a set time;
- not blocking the phone with the network after theft;
- devices bought second-hand or not in the policyholder's name;
- a limit on the number of claims per year.
Example
A student's phone is stolen from a café table while they go to the counter. Their insurer refuses the claim because the phone was left unattended. A friend whose phone was snatched from their hand on the street has their claim accepted under the same kind of policy.
How claims work
Claims are usually made online or by phone. The insurer may ask for proof of purchase, a crime reference number for theft, confirmation that the phone has been blocked, and the damaged device for inspection. Replacements are often refurbished models or equivalent devices rather than brand-new ones of the same model. Delays and refurbished replacements are among the most common complaints.
Repair, refurbished and second-hand options
Instead of insurance, some people keep a repair fund, buy a sturdy case and screen protector, or use independent repair shops, which are often cheaper than manufacturer repairs. Rules in several countries are making repairs easier by requiring manufacturers to supply parts and repair information. Refurbished phones, which cost less to replace, also change the calculation.
Example
A parent buys each of their teenagers a refurbished phone, a thick case and a screen protector, and keeps a small repair fund instead of paying for insurance. Over three years they pay for two screen repairs and still spend less than the insurance would have cost.
Protecting data as well as the device
Losing a phone often means losing more than the device. Photos, messages, contacts, banking apps and two-step login codes may all be on it. Insurance replaces the hardware, not the data. Many people now treat backups, screen locks and remote wipe features as just as important as insurance. Turning on a phone's location and lock features can also help police and insurers when a device is stolen, and in some countries networks share lists of stolen phones so they cannot be used again.
Business and family policies
Some insurers offer policies that cover every device in a household, or all the phones and laptops used by a small business, for one premium. These can be cheaper per device but often have claim limits for the whole policy. Families with several children's phones and small firms whose staff use their own devices are the main buyers.
What people disagree about
Consumer groups often say gadget insurance and extended warranties are poor value for many buyers and that pressure selling at the till is a problem. Others say cover gives peace of mind and protects people who could not afford a sudden replacement. Insurers point out that phone theft and damage are common and that the cost of repairs has risen.
Questions that businesses want answered include how many people insure their phones, who they buy cover from, whether they know what home or bank cover they already have, how many have claimed, and how satisfied they were with the outcome.
Key terms
- Gadget insuranceInsurance for phones and other devices against damage, theft and sometimes loss.
- Extended warrantyCover for faults after the manufacturer's warranty ends.
- Accidental damageDamage caused by an accident, such as a drop or spill.
- ExcessThe amount the policyholder pays toward each claim.
- UnattendedLeft where the owner cannot see or control it, a common exclusion.
- RefurbishedA used device that has been checked, repaired and resold.
- BlockingAsking the network to stop a stolen phone from being used.
- Duplicate coverPaying for the same protection through more than one product.
Full glossary: personal lines insurance terms on EditingTests.com.
Mobile phone and gadget insurance vocabulary test
How well do you know the language of this topic? Try 8 quick questions. Your score is shown straight away and is not saved.
What the mobile phone and gadget insurance survey asks
This survey is part of ModQu's Insurance survey. The mobile phone and gadget insurance part takes about five minutes and covers:
- Whether your phone or other devices are insured, and by whom.
- How much you pay and what excess applies.
- Whether you know what your home, bank or card cover includes.
- Whether you have claimed for damage, loss or theft, and how it went.
- Why you chose insurance, or chose not to.
- What you would do if your phone were broken or stolen tomorrow.
After that you can choose to continue with other short parts of the Insurance survey, such as car insurance or home and tenant insurance, or stop.
Ready to take part?
Your answers help show what people really think and do. Results are only ever reported as totals; no one can see your individual answers.
Start the surveyQuestions about this survey
Who can take part?
Adults who own a smartphone.
Do I have to give my name?
No. You may be asked for your age group, region and similar details so results can be broken down, but not your name. ModQu never asks for passwords, card numbers or account numbers.
How are the results used?
Answers are combined into totals and percentages and published in ModQu reports. Individual answers are never shown.
Is the vocabulary test part of the survey?
No. It is optional and separate, and your score is not stored.
Does home contents insurance cover my phone?
Sometimes inside the home, and outside only with an add-on. Check your policy.
Is an extended warranty the same as insurance?
No. Warranties usually cover faults only, not accidental damage, loss or theft.